

Audio
Cutting To The Chase
So how was the West won? By an extraordinary burst of real economic development, supercharged by money and credit. It helped build modern America. It also produced a Credit Bubble.
The 1830s are astonishingly modern. Central banking, money creation, asset bubbles, leverage, government debt, foreign creditors, bailouts and the question of who pays when it all goes wrong. Change the names and we are still arguing about much the same things today.
The development was real and so was the bubble. In fact, genuine economic success can make a credit bubble even more dangerous because for a while the prosperity seems to justify all that borrowing.
Jackson destroyed the Second Bank but not fractional reserve banking. Changing who creates and controls the credit does not solve the underlying monetary problem. This is exactly the debate surrounding the Fed today.
So what actually disciplines money and credit creation? In the 1830s specie and the balance of payments eventually imposed a constraint that banks and politicians had managed to postpone. Today? Nothing really.
You don’t need leverage to grow. Credit can accelerate development, but it can also distort the Allocation of Resources and encourage us to borrow far too much against an imagined future.
The debts are fixed. The future isn’t. When asset prices, incomes and collateral collapse, the debts remain. Therein lies much of the history of financial crises.
Governments can get caught in exactly the same trap. They can borrow against future prosperity just as enthusiastically as farmers, speculators, banks and corporations.
Debt to GDP can be deeply misleading. Nine American governments stopped paying when total state debt was only around 12 percent of GDP. Debt is serviced from money governments can actually obtain, not GDP.
And what do we do when a credit bubble bursts? Apparently, create more credit. 1837 meet 2007.
Which leaves the oldest argument of all. Once the losses exist, somebody has to take them. Default, bailout, taxation, restructuring and inflation merely change who that somebody is.
The 1830s aren’t ancient history. They are a remarkably good guide to the monetary and political mess we are still arguing about today.
What a diabolical ideological mess.
It’s the Money System (Again!)
If this music doesn’t make you want to build a railroad, dig a canal or head west and start something, nothing will. There are lots of musical themes from Westerns that we can associate with that pioneering, go get ‘em’ spirit that built the U.S. West (warts and all). But for me, it is this one.
So, shall we get in our wagon and begin the journey to see how the West was won? As you might expect, the money system was front and center.
The Unfinished Argument Over Money
The Panic of 1819 left the United States with a problem much larger than the failure of a few banks or the collapse of a speculative boom. Americans had to decide what had gone wrong with their monetary system.
The Second Bank of the United States, the Fed Mark II, had been created in 1816 with a twenty year mandate partly to restore order after the suspension of specie payments and enormous expansion of state banking during the War of 1812.
Yet the new national bank had itself participated in the postwar expansion before suddenly reversing direction and helping impose the contraction that followed.
You can read all about it in my essay below. Same old story really: creating money from nothing through government combined with fractional reserve banking, creating a bubble and the inevitable disaster that follows.
Unlike Today, At Least They Had A Real Debate
One figure captures the problem. By July 1818 the Second Bank had approximately $21.8 million of notes and deposits outstanding against only about $2.4 million of specie. When it finally became concerned about its reserves, it contracted lending, collected debts and demanded specie from state banks. Borrowers who had entered commitments during the expansion suddenly had to obtain much scarcer money to repay debts whose nominal value had not changed.
The result was a monetary argument that would dominate American politics for decades. Supporters of the Second Bank concluded that the chaos demonstrated the need for a powerful national institution capable of disciplining state banks. Opponents could reply that the Second Bank had helped create the expansion before inflicting the contraction.
Even the Opponents Disagreed Amoungst Themselves
Some wanted easier money and debtor relief. Others reached almost the opposite conclusion: harder money, stricter specie redemption and less bank created credit.
Underneath all of this was the question that still has not gone away. If banks can create notes and deposits far beyond their monetary reserves, what prevents the banking system as a whole from creating too much money and credit?
The Hole In Jackson’s Solution
Am I the only one who sees the irony of central bankers having their annual love in at a place called Jackson Hole? I mean, President Andrew Jackson is probably history’s most famous political nemesis of central banking.
There are eerie echoes between the Jacksonian debates of the 1820s and 1830s and today’s arguments over the Fed, its independence and political attempts to change its direction. You will see what I mean as we go through the story.
Jackson believed that the concentration of monetary power in the Second Bank was itself part of the problem. But destroying an institution is not necessarily the same thing as solving the monetary mechanism underneath it. If the Second Bank disappeared, what would prevent hundreds of state banks from creating the same credit somewhere else?
That was about to become a very expensive experiment.
The Creditors Versus Debtors Fight.
There was another problem left behind by 1819. What do you do after a credit bubble has already burst?
A farmer who bought land during the boom could emerge from the collapse with exactly the same dollar debt but much lower commodity prices, much less money circulating and land worth considerably less than when he borrowed. From his perspective, debtor relief seemed perfectly reasonable. The creditor saw things differently: he had advanced money under a contract specifying repayment in dollars, and retrospective legislation could simply transfer the borrower’s loss onto him.
It Is As Old As Credit Itself
Go back to ancient Egypt or China and you find versions of the same argument. What about the farmer destroyed by a failed harvest? What about the speculator who borrowed to make a fortune from rising land prices? What about the creditor who lent recklessly? And what about completely innocent people who lose their jobs and businesses when the whole thing collapses?
I know. How about not creating the credit bubble in the first place?
But Decisions Need To Be Made
Unfortunately, once it has happened, there are real decisions to make. Protect the creditors? Rescue the debtors? Let the banks fail? Inflate the money supply? Restructure the debts? Default? Tax people who never borrowed the money to repay people who lent it?
The states responded after 1819 with various combinations of stay laws, appraisal requirements, state loan offices and paper money. Kentucky’s attempts at debtor relief even produced the extraordinary Old Court New Court controversy when the legislature tried to replace a court that had struck down parts of its programme.
It is the same basic problem I dealt with after the Revolution and Shays’ Rebellion in my essay below.
The important point for our story is that the argument produced two very different kinds of opponents of the Second Bank. Some disliked it because it restricted credit when debtors desperately wanted more. Others, including hard money critics such as Hezekiah Niles and Condy Raguet, thought excessive paper money had created the bubble in the first place and wanted stricter specie redemption and less bank created credit.
And America was about to confront the creditor debtor problem again on a much larger scale. This time some of the biggest debtors would be the states themselves.
What Disciplines A Bank?
This brings us to the central monetary problem.
A fractional reserve bank can create more notes and deposits than it holds in specie, but one bank cannot expand indefinitely. If it expands much faster than its competitors, its new money eventually reaches customers of other banks. Those banks demand settlement and the expanding bank begins losing its gold or silver reserves.
But What Happens If Most Of the Banks Expand Together?
Interbank claims increasingly cancel through clearing and that particular restraint becomes weaker. The discipline then has to come from outside the banking system. Individuals can demand specie and, crucially, payments to foreigners can cause specie to leave the country. In that sense, the balance of payments can discipline an entire national banking system much as competing banks discipline an individual bank.
Even that only works if redemption is actually enforced. As Condy Raguet explained to Ricardo in 1821, depositors and borrowers often had strong incentives not to demand specie, while governments repeatedly permitted banks to suspend payment when the pressure became severe.
Gold and silver therefore provided an ultimate constraint, but politics could weaken that constraint precisely when it began to bite.
That was the monetary system Andrew Jackson was about to take on.
Who Disciplines the Disciplinarian
The Second Bank survived the Panic of 1819 largely because its new president, Langdon Cheves, brutally tightened lending, collected debts and rebuilt its specie reserves. Nicholas Biddle, who took over in 1823, then transformed it into a much more effective national institution. Meanwhile, McCulloch v. Maryland (1819) had confirmed Congress’s constitutional authority to charter the Bank and prevented states from taxing it out of existence.
The Economic Case Seemed Straightforward
America had hundreds of banks issuing notes of varying quality, often trading at discounts far from their place of issue. The Second Bank provided a more widely accepted currency and, crucially, could collect state banknotes and demand their redemption in specie. A state bank expanding too aggressively could therefore find Biddle’s Bank knocking on its door demanding hard money.
But the Bank was itself a fractional reserve bank, creating notes and deposits against a smaller specie reserve. This produced the fundamental dilemma. If hundreds of banks could not adequately discipline themselves, a national bank seemed useful. But if the solution was to give one enormously powerful bank the ability to discipline all the others, who disciplined it?
Then There Was the Small Matter of Power
The federal government owned one fifth of the Bank and deposited its money there, while most of the institution remained privately owned and some shareholders were foreigners. Biddle was unelected, yet decisions made in Philadelphia could influence credit conditions across the country. Supporters regarded this independence as a strength. Opponents regarded it as a danger.
The Erie Canal Illustrates the Spirit of the Times
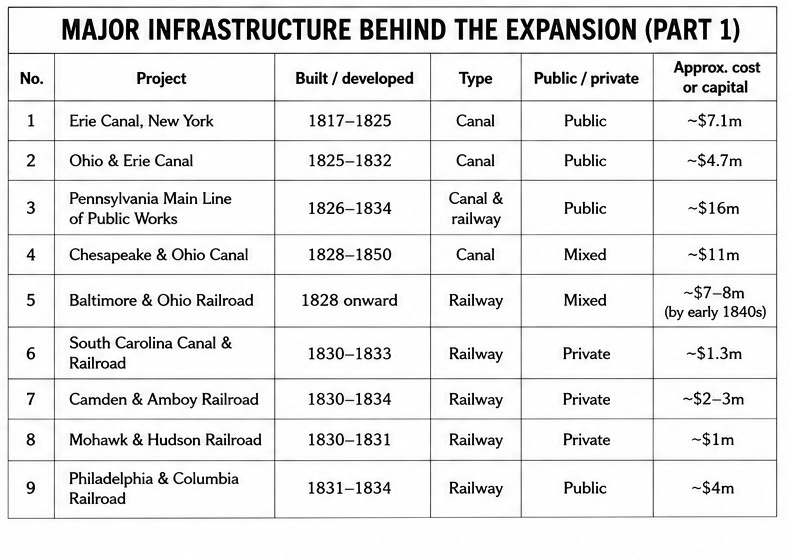
The Erie Canal showed what could happen when the borrowing actually worked. New York financed much of the project with state debt, spending about $7.1 million to connect the Hudson River with Lake Erie. When it opened in 1825, transport costs between the Great Lakes and the Atlantic collapsed, western produce could reach eastern and European markets far more cheaply, and manufactured goods could move west just as dramatically.
The Economic Consequences Were Enormous
Trade surged, towns grew along the route, western land became more valuable and New York collected substantial toll revenues. The canal did not merely make its debt manageable; it appeared to demonstrate that a state could borrow heavily, build infrastructure, create economic growth and use the resulting prosperity to repay the borrowing.
What politician wouldn’t want some of that? Canals, roads and later railways suddenly looked less like government expenditure and more like investments in a much richer future.
The trouble was that every state now wanted to be New York.
The Voice Goat Sets the Scene For the 1830s
Here is a very short video on the main events of 1830s America to set the scene.
Jackson and Biddle. Sort of Like Trump and Powell.
Andrew Jackson entered the presidency in 1829 deeply suspicious of banks, debt and concentrated financial power. The confrontation came in 1832 when Henry Clay and Biddle sought an early renewal of the Bank’s charter. Congress approved it and Jackson vetoed it, attacking monopoly privilege, foreign ownership and the extraordinary concentration of financial power in a federally privileged private institution. He then won re-election decisively.
Jackson subsequently removed federal deposits from the Second Bank and redirected new government receipts into selected state institutions, the so-called pet banks. Biddle responded by tightening credit, partly from financial necessity but also in the belief that the resulting distress would demonstrate the Bank’s importance and force Jackson to retreat.
That produced the great irony of the Bank War. Biddle could argue that the resulting distress demonstrated why America needed his Bank. Jackson could reply that the ability of one unelected banker to tighten credit across the country to influence government policy demonstrated precisely why it was dangerous.
Jackson won. The federal charter expired in 1836. But moving government money from one enormous fractional reserve bank into numerous smaller ones had hardly solved the underlying monetary problem.
What Happened After Jackson Won?
The aftermath provides a useful test of both arguments. If the Second Bank had been causing the instability, its destruction should have improved matters. If it had been restraining the state banks, removing it should have encouraged further expansion.
Expansion certainly followed. The American money supply rose from approximately $150 million at the beginning of 1833 to about $267 million by early 1837, an increase of almost 80 percent. State banking expanded, credit increased and land speculation accelerated.
But this was not simply banks creating more paper against an unchanged quantity of metal. America’s specie stock also surged from approximately $31 million to $73 million. Mexican silver and changing international silver flows played important roles, giving the banking system a much larger metallic base upon which to expand credit.
The Results Were Spectacular
Federal public land sales, previously around $4–6 million annually, jumped to $16.2 million in 1835 and $24.9 million in 1836. More specie supported more bank credit; credit financed land purchases; rising land prices strengthened collateral; and expectations of continuing western expansion encouraged still more borrowing.
Jackson had destroyed the Second Bank. He had not destroyed the credit cycle.
Back Home In the Cotton Fields
There was a perfectly sound economic reason for the boom. Britain’s Industrial Revolution created enormous demand for American cotton just as production was moving west into the fertile lands of Alabama, Mississippi and Louisiana.
It is impossible to make sense of the American cotton industry (and indeed the expansion Westward) without understanding the Industrial Revolution which began in Britain. Watch the above video for a refresher. It is equally impossible to understand the slavery situation in the U.S. without understanding the cotton industry. See the video below for that.
Of Course There is the Slavery Issue
With All This In Mind…
Cotton prices rose from roughly 10 cents a pound in 1830 to 15 cents or more in 1835, while exports increased in value from about $30 million to more than $71 million by 1836. Production surged from roughly 977,000 bales in 1830 to 1.42 million in 1837 and more than 2 million by 1840.
Credit allowed this expansion to happen much faster. Planters borrowed to buy land, enslaved people and supplies, using land and future crops as collateral. Cotton factors and merchants advanced money against crops, while bills drawn against shipments were discounted through New Orleans, New York, Liverpool and London. Rising cotton and land prices increased collateral values, supporting still more borrowing and production.
Credit also allowed merchants to finance cotton inventories rather than sell immediately.
Go West Young Man. Build, Build, Build.
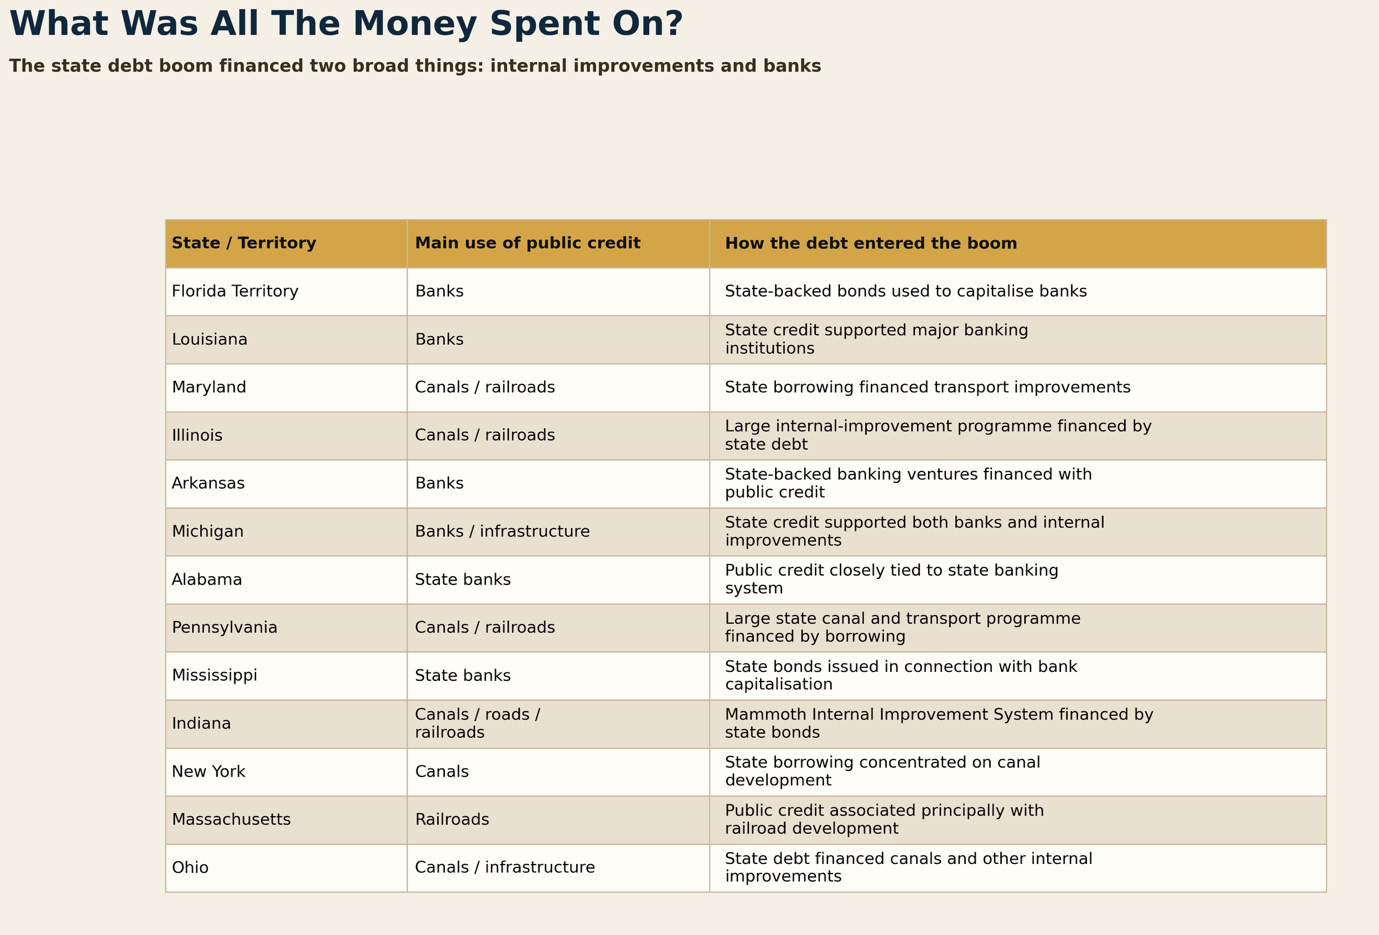
But cotton was only part of the enormous expansion westward. Settlers and speculators borrowed to buy federal land; farmers borrowed to establish farms; merchants financed the new communities; and states borrowed to build the canals, roads and railways connecting them to markets. Some states also borrowed to establish or capitalise banks.
The logic seemed compelling. Borrow today, build the infrastructure, open new territory, increase land values and commerce, and repay the debt from tolls and the revenues of a much richer future state. The Erie Canal, completed for about $7.1 million, appeared to prove that it could work.
That’s Not Leverage. This Is Leverage
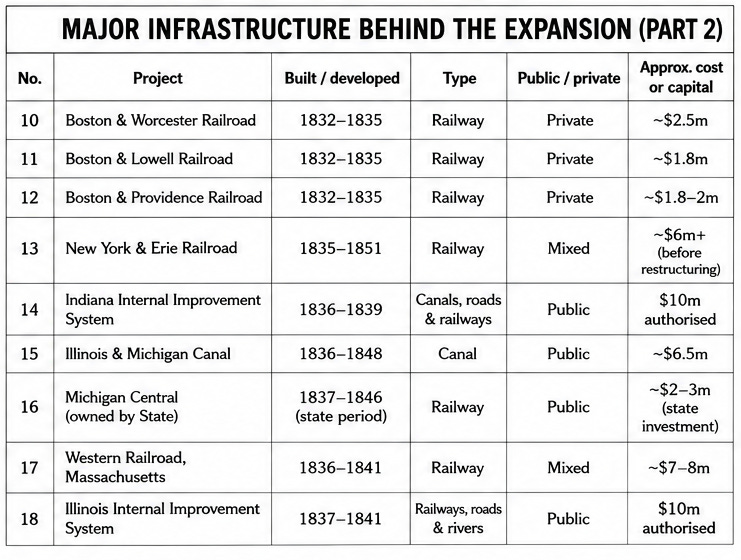
But some states took the idea to extraordinary lengths. Indiana authorised $10 million for internal improvements in 1836 when annual state tax revenue was only around $50,000. Illinois followed with a $10 million programme when annual state revenue was around $57,000. They were borrowing not against the economies they had, but against the much larger economies they expected to create.
Teachable Moment. You Don’t Need Leverage To Grow.
This is the important distinction between genuine economic development and a credit bubble. America really did need more cotton, western farms, canals and railways. Much of it would have happened anyway. Credit did not invent the economic transformation; it accelerated it and affected how resources were allocated.
Without such rapid credit growth, cotton production probably would have expanded more slowly, and infrastructure projects would have competed more vigorously for scarce capital. The Erie Canal would surely still have been built. Whether Indiana would simultaneously have attempted its enormous Mammoth Internal Improvement System is another question.
Nothing New Under The Western Sun
By the middle of the 1830s the cotton, land, banking and infrastructure booms were feeding one another. Credit pushed up land and cotton prices; higher asset prices supported more credit; infrastructure increased western land values; and British demand and capital helped finance the entire process.
The weakness was simple: the debts were fixed while the values supporting them were not. This is a movie we have seen many times in history. Cotton prices could fall, land values could collapse and projected canal tolls could fail to appear, but the loans and bonds remained.
The Crash Came In 1837
The trigger came from both sides of the Atlantic. The Bank of England, worried about declining gold reserves, tightened credit during 1836 just as increasing quantities of American cotton were arriving in Britain. American related bills became harder and more expensive to finance. Merchants who had previously borrowed to carry their cotton inventories suddenly needed cash and began selling.
The Process Then Fed Upon Itself
Cotton prices fell, reducing the value of the cotton behind existing loans and bills. A shipment expected to realise £10,000 might now be worth only £8,000 even though £10,000 had already been advanced against it. Lenders became more cautious, credit contracted further, more cotton had to be sold and prices fell again.
The shock travelled back across the Atlantic. American banks and merchants had lent against rising cotton and land prices, so falling cotton prices weakened collateral and threatened the bills and loans built upon it. At the same time the American land boom was already vulnerable and banks faced increasing pressure on their specie reserves. What had been a self-reinforcing credit expansion began working just as powerfully in reverse.
In May 1837 the New York banks suspended specie payments and the suspension spread across much of the country. The cotton, land and banking boom had finally broken.
But the interesting part for what follows is what happened next. Rather than simply allowing the credit structure to unwind, America found ways to start expanding credit again. And this time the states themselves would be right in the middle of it.
Are You Thinking 2007? Solve A Credit Crash By Creating More Credit.
The financial system did not simply liquidate the debts and start again. Banks suspended specie payments, meaning their notes and deposits could no longer necessarily be converted into gold or silver on demand, while various forms of credit were used to keep commerce moving.
Nicholas Biddle’s Bank of the United States of Pennsylvania became particularly aggressive, including issuing post notes promises to pay at a future date rather than ordinary notes payable immediately in specie.
These could circulate or be discounted and therefore provided another way of extending credit when specie payments and conventional bank finance were under severe pressure.
What Could Possibly Go Wrong?
At the same time, borrowing did not disappear. It increasingly reappeared in other forms and in other places. State governments and state supported banks continued raising enormous sums, much of it through bonds sold to American and British investors, to finance banks, canals, railways and other internal improvements.
In effect, the economy was trying to escape one credit crisis while another enormous structure of debt was still being built.
That Distinction Is Imposrtant
The Panic of 1837 was the immediate banking and commercial crash. The Crisis of 1839 exposed something deeper: debts had migrated and accumulated throughout the states, banks, land market and internal improvement programmes. When credit tightened again, some states discovered that the future revenues against which they had borrowed simply did not exist.
And that brings us to the extraordinary part of the story: the state debt crisis.
The Borrowing Had Moved To the States
The Panic of 1837 was severe, but there was enough recovery during 1838 for many contemporaries to believe that the worst had passed. Banks resumed specie payments in many places, commerce revived and, remarkably, state governments continued borrowing on an enormous scale.
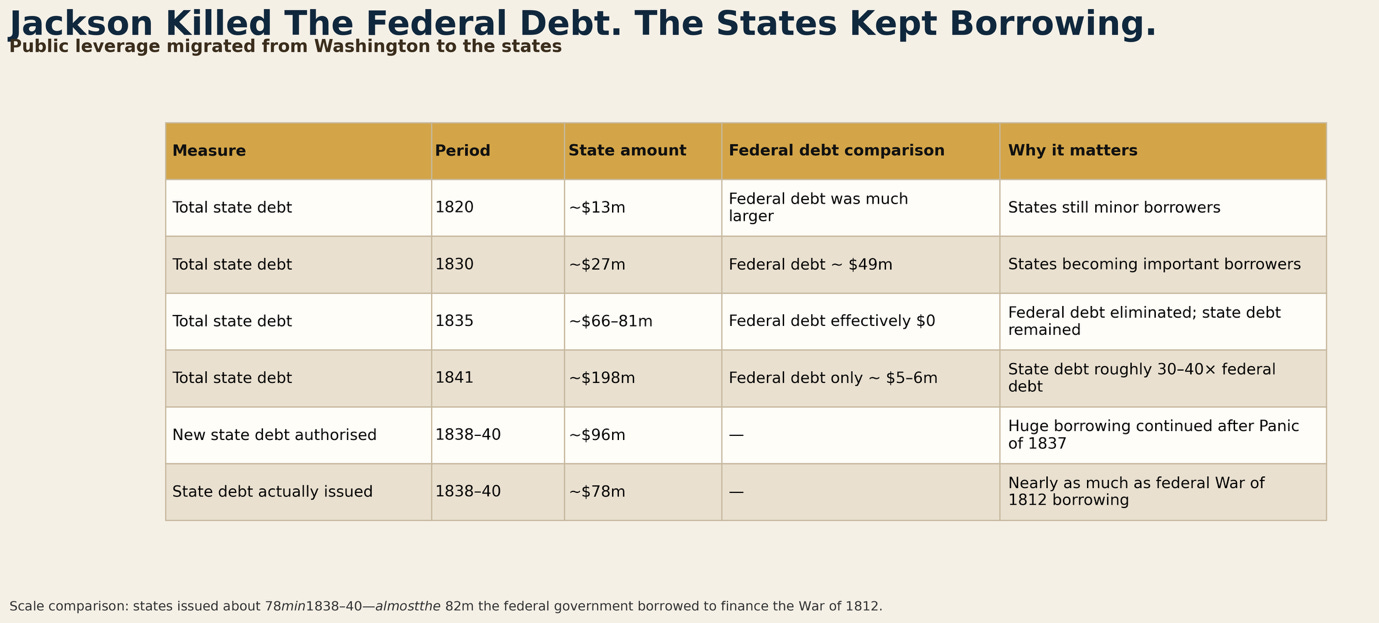
During 1838, 1839 and 1840 the states authorised approximately $96 million of additional debt and issued around $78 million. To put that in perspective, Washington had borrowed approximately $82 million to finance the entire War of 1812.
State debt had been only around $13 million in 1820 and $27 million in 1830. Estimates vary somewhat, but by 1835 it was approximately $66–81 million and by 1841 around $198 million. Jackson had extinguished the federal debt, but America had certainly not stopped borrowing.
Let’s Default. And the Problem Is?
Nine Governments Stop Paying
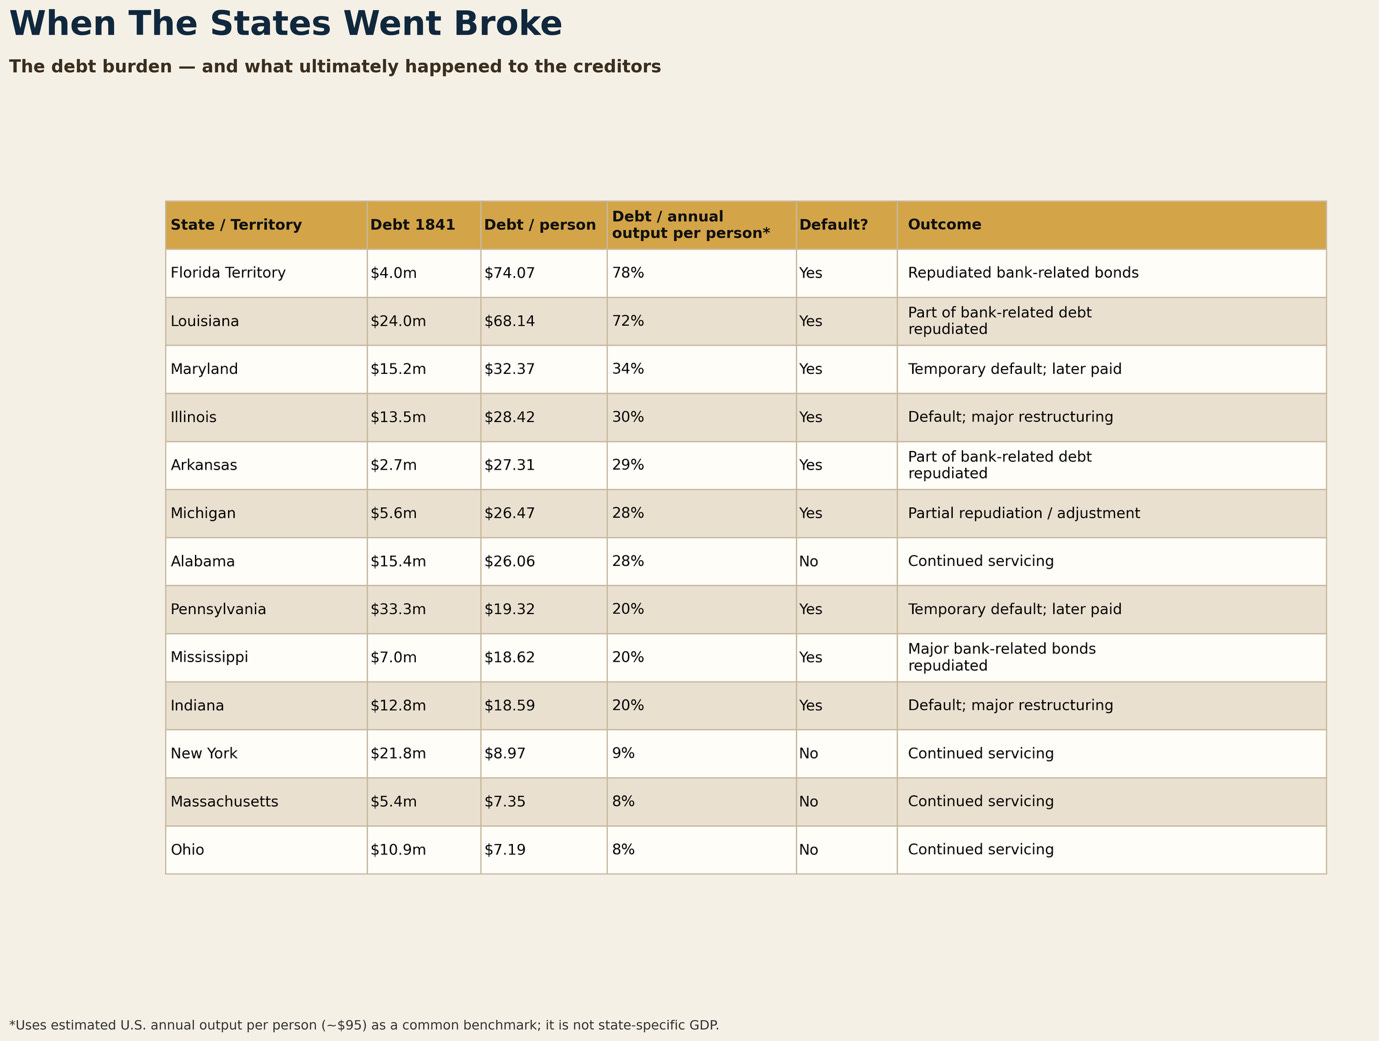
By 1841 and 1842 eight states and the Territory of Florida had defaulted: Pennsylvania, Maryland, Indiana, Illinois, Michigan, Arkansas, Mississippi and Louisiana, together with Florida, which did not become a state until 1845.
Total state debt of approximately $198 million was only around 12 percent of estimated American GDP. By modern standards that sounds almost trivial.
So how did so many American governments default with aggregate debt equivalent to only about 12 percent of national output?
Governments Do Not Service Their Debts Out Of GDP
The answer begins with the denominator. Debt is not serviced out of GDP. It is serviced from government revenue, investment income, asset sales, new borrowing or some other source of funds available to the government.
Antebellum state governments were tiny institutions by modern standards. Their tax systems were narrow, administrative machinery limited and political resistance to direct taxation often intense. Some development programmes had been deliberately designed around the expectation that canals, banks, land values and future growth would service much of the borrowing without requiring enormous immediate taxes.
Why Couldn’t They Just Print The Money?
This takes us directly back to the monetary question at the centre of the story. Why didn’t the states simply create the money required to pay their debts?
The answer requires a distinction between creating credit and creating the asset in which that credit ultimately had to be settled. State governments could charter banks, and those banks could certainly create notes and deposits. Several states were directly involved in banking institutions. There was therefore no absolute prohibition on the creation of additional monetary claims.
But a Banknote Was a Promise To Pay Specie
A bank deposit was ultimately a claim on a bank promising redemption in specie. Creating another million dollars of banknotes created another million dollars of liabilities. It did not create another million dollars of gold or silver.
During the boom this distinction could disappear because people were willing to hold the promises. During the contraction everybody began asking what stood behind the promises.
A state could issue another bond and use the proceeds to pay interest on an earlier bond, but only while somebody was prepared to buy it. A state bank could create additional notes, but if holders demanded redemption the bank required specie. British bondholders did not have to accept an unlimited quantity of Indiana banknotes as final payment.
Oh, the Foreigners Matter
The foreign ownership of state bonds made the constraint particularly obvious. International payments ultimately required financial claims acceptable abroad or, at the end of the settlement chain, gold or silver.
The states could create credit, but they could not create the ultimate settlement asset.
That made their position fundamentally different from that of a modern sovereign government issuing debt in a fiat currency it controls.
The Latin America Of Their Day
The modern United States government cannot create real resources without limit, and excessive monetary financing can produce inflation, depreciation and loss of confidence. But it cannot involuntarily run out of nominal dollars in the same sense that Indiana could run out of the specie or internationally acceptable funds required to meet its obligations.
The nineteenth century states therefore faced something closer to the problem of a modern government borrowing in a currency it cannot create. In short, they were the 1980s Latin America of their day.
Once lenders refused to refinance them, their choices became brutally limited: tax, sell assets, borrow somewhere else, restructure or default.
Tax, Default Or Repudiate. That Is the Question
The different outcomes among the states demonstrate the importance of fiscal capacity. Pennsylvania and Maryland defaulted temporarily but ultimately imposed effective property taxation, resumed payments and honoured their debts. Their underlying economies contained substantial taxable resources; the governments had simply failed to construct adequate revenue systems before the crisis.
Indiana and Illinois Faced a Harder Problem
Their ambitious development programmes had been financed partly against the future population, land values and tax bases that the projects themselves were expected to create. Indiana substantially increased property taxation, but it was attempting to tax more heavily while the value of the property being taxed was collapsing. Both states ultimately restructured their obligations.
Several southern cases were different again because state bonds had been issued to support banks. The banks were expected to service the obligations from their own profits. When they failed, what had looked like a self-financing arrangement suddenly became a claim against taxpayers. Mississippi became the most notorious case, repudiating major bank related obligations, while Florida and several other governments also repudiated or failed to repay portions of particular debts.
Not Every Heavily Indebted State Defaulted
New York owed almost $22 million and continued servicing its debt. Ohio owed nearly $11 million and also avoided default, substantially increasing taxation. Alabama carried more than $15 million without formally defaulting at this stage.
Debt alone therefore did not determine the outcome. The structure of revenues, unused taxing capacity, quality of the investments, exposure to failed banks, ability to refinance and political willingness to impose taxes all mattered.
Deflation Turns The Screw
The monetary contraction made every part of the fiscal problem worse. Historical estimates suggest that the American money supply fell from approximately $240 million at the beginning of 1839 to around $158 million in 1843, a decline of roughly one third. One historical price index falls by more than 40 percent between early 1839 and early 1843, while the number of banks also declined substantially.
The crucial point is that debts did not fall with prices. If Indiana owed $12 million, a collapse in land values did not reduce the bonds proportionately. Interest remained contractually due in nominal dollars even while property prices, wages, toll revenues, bank collateral and the taxable base were falling.
The Debt Burden Increases
The real burden of the debt therefore increased precisely as the resources available to service it contracted. Banks responded to deteriorating collateral by restricting credit and collecting loans. Borrowers sold assets into falling markets. Lower asset prices further damaged collateral and tax bases, encouraging still more contraction.
The same mechanism visible after 1819 had returned on a much larger scale. This time governments themselves were among the leveraged borrowers.
Washington Says No
The defaults created an American sovereign debt crisis with international consequences. British and European investors discovered that bonds issued by American states were not guaranteed by the United States government. Pennsylvania could default without Washington paying Pennsylvania’s creditors, and Mississippi could repudiate obligations without the federal Treasury making the bondholders whole.
Demands consequently arose for federal assumption of the state debts. There was an obvious precedent: Alexander Hamilton’s assumption of Revolutionary War state obligations in 1790. But Washington refused.
No Federal Bailout. Deal With It
A federal bailout would have transferred losses from heavily indebted states and their creditors onto national taxpayers, including citizens of states that had borrowed much less. Instead, the states and their creditors largely had to absorb the consequences themselves. Some states raised taxes, others restructured or repudiated their debts, and during the 1840s and 1850s many introduced constitutional restrictions on future borrowing.
And That Brings Us To Where We Started
The development of the West was real. The farms, cotton, canals, roads and railways were real. But the monetary system allowed an enormous structure of credit to grow around that development. Banks created money against rising land and commodity values, while states borrowed against the tolls, population, tax revenues and prosperity they expected to arrive in the future.
That was Credit Bubble Number Two. When it burst, cotton and land prices fell, collateral collapsed, banks contracted credit and the money supply shrank. But the debts remained. Andrew Jackson had destroyed the Second Bank, but he had not destroyed fractional reserve banking or the credit cycle.
Who Should Pay?
Which leaves the question that has followed credit bubbles throughout history: who pays?
The debtor can pay through bankruptcy and foreclosure. Creditors can pay through default or restructuring. Taxpayers can pay through higher taxes or bailouts. Holders of money can pay through inflation and depreciation. Or the losses can be shifted onto people who had nothing to do with creating the debt in the first place.
There is no magic solution in which the loss disappears. Default, bailout, taxation, restructuring and inflation merely distribute it differently. That is the default position on default.
What a diabolical ideological mess.